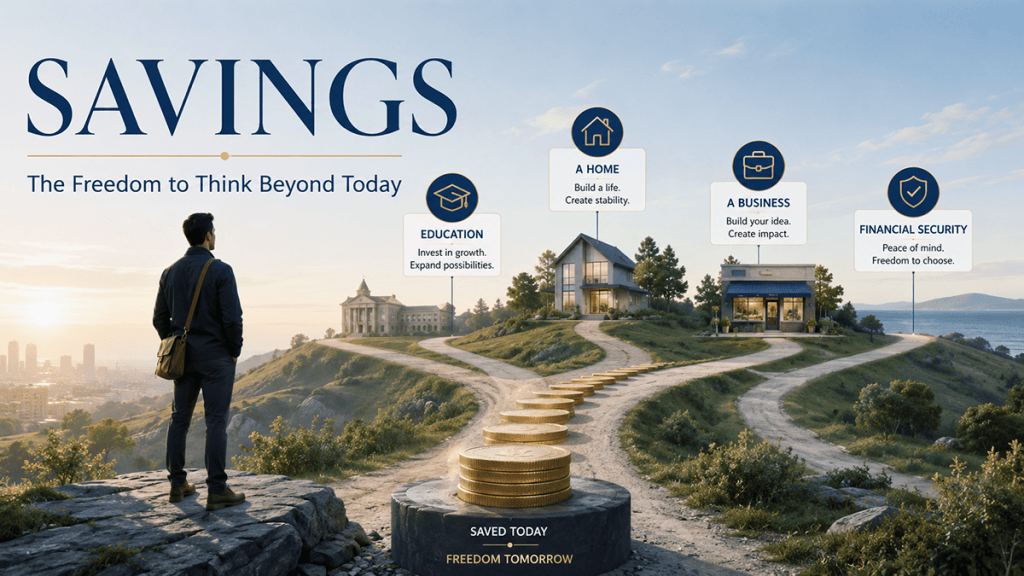
Savings are stored choices.
Savings are often described as money you did not spend.
True, but incomplete.
Savings are choices you have not yet made.
Every dollar you save preserves part of your past production for a future purpose. Consumption answers today’s wants. Savings preserve tomorrow’s options.
That distinction matters.
A PERSON WITH SAVINGS HAS MORE ROOM TO CHOOSE
Consider two people with the same income.
One spends nearly everything each month. The other regularly sets aside part of each paycheck.
Their incomes match. Their freedom does not.
The saver has a reserve between an unexpected event and immediate dependence on someone else. A repair bill, temporary loss of income, family need, or business opportunity becomes a problem to manage rather than an instant crisis.
Savings also strengthen your ability to say “No.”
- No to a bad loan.
- No to a job you no longer want.
- No to a purchase beyond your means.
- No to a business deal made from desperation.
- Yes to an opportunity worth pursuing.
Savings buy time. Time gives judgment room to work.
SAVINGS ARE NOT HOARDED CONSUMPTION
Saving often gets described as postponed spending. In one sense, the description fits. You give up some present consumption in exchange for greater future choice.
“Hoarding” misses the point.
Saving does not necessarily remove resources from productive life. Savings held in bank deposits often support lending, while savings invested in bonds, retirement accounts, or businesses supply capital.
Saving and investing are related but distinct.
Saving means preserving part of current income rather than consuming it.
Investing places some of those saved resources at risk in pursuit of a return.
Saving often makes investing possible.
Before someone invests in a business, buys equipment, funds an education, or makes a down payment, resources first need to exist.
Savings create the reserve from which future action begins.
THE RIGHT TO YOUR OWN TIME HORIZON
A free society leaves the time horizon to you.
You decide how much of today’s income should serve today and how much should serve tomorrow.
A young entrepreneur building a reserve, a family preparing to buy a home, and a worker approaching retirement all face different needs.
No single savings rate fits every life.
The principle matters more than the percentage.
Your income represents your productive effort. After meeting your obligations, you decide how much to consume, save, invest, give away, or reserve for later.
WHAT SAVINGS GIVE YOU
Savings expand your range of action.
They give you time to search for a better job instead of taking the first offer.
They help fund a new business, education, relocation, or another opportunity.
They reduce pressure to rely on expensive debt after an emergency.
They strengthen your bargaining position because desperation no longer controls every decision.
They provide resources for people and purposes you value.
Savings do not guarantee success.
They preserve alternatives.
THE FREEDOM TO WAIT
Markets reward action. Wise action sometimes means waiting.
You do not have to buy today.
You do not have to sell today.
You do not have to accept today’s offer.
You do not have to borrow today.
A financial reserve gives you room to wait for better information, a better price, or a better opportunity.
Someone living at the edge of every paycheck has less room for patience.
This does not make saving a moral duty measured by an account balance. Circumstances, income, and obligations differ.
The principle stays clear.
Greater financial margin gives outside events less power to dictate your next move.
INFLATION: WHEN SAVED DOLLARS LOSE PURCHASING POWER
Savings preserve future choices, but inflation affects how many choices those savings will buy.
If prices rise faster than your savings grow, your account balance may increase while its purchasing power still falls.
This means saving alone does not always protect long-term financial independence.
Short-term reserves serve one purpose. Long-term capital serves another.
Emergency savings need liquidity and stability. Money intended for years or decades in the future often needs to earn returns that keep pace with inflation if you want to preserve purchasing power.
Financial freedom therefore requires another decision.
You must decide not only how much income to preserve, but how to protect the future value of what you preserve.
Savings store choices. Inflation reminds you that stored choices need protection.
SAVING IS PURPOSEFUL, NOT ENDLESS
Saving has a purpose.
Money serves life. Life does not serve an account balance.
The goal is not endless accumulation while refusing every present enjoyment. The goal is conscious choice about which values belong to today and which deserve preparation for tomorrow.
Some savings protect you.
Some prepare you.
Some become investments.
Some become future consumption.
All represent the same underlying act. Part of today’s production stays available for a future choice.
For me, the best description remains simple.
Savings are stored choices.
Key Idea
Savings preserve future choices and give your judgment more time, independence, and room to act.
Read Next
Related Articles
Continue exploring
Individual Capitalism is a connected Library. Follow the next article, explore a Reading Path, or browse the complete collection.

